ISLAMABAD: Finance Minister Ishaq Dar insisted on Thursday that record depreciation in the value of the rupee a day earlier was ‘artificial’, far from economic fundamentals and caused by ‘miscommunication’ between an individual and the central bank.
The State Bank of Pakistan held its silence throughout the day, and its spokesman refused to comment. The interbank rate was 105.7 at close on Thursday.
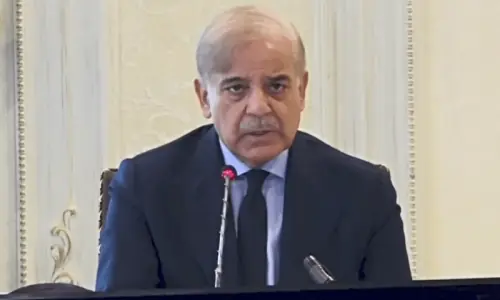
After presiding over a meeting of presidents and chief executive officers of almost all the banks, the finance minister appeared to put the blame, without naming, on the acting governor of the central bank for “almost causing a colossal loss of Rs230 billion in the shape of increased public debt” due to devaluation of the rupee against the dollar. The acting governor was conspicuous by his absence, nor did the finance minister mention his name when listing the people he spoke with to get a better handle on the situation.
He told media persons outside the finance ministry that independent investigations and inquiry would be conducted into the incident that caused “a mind-boggling” setback to the foreign exchange markets, devaluing the currency by Rs3.50 per dollar within a few hours. “Action will be taken in the light of the inquiry report in about 10 days,” he said.
Tariq Bajwa’s appointment as SBP governor approved
In a late-night development, the appointment of Tariq Bajwa, who recently retired as finance secretary, as State Bank of Pakistan governor was approved, according to officials. A notification in this regard is expected soon.
Mr Dar said that around two dozen heads of banks, the deputy governor banking and head of treasury of the SBP besides senior officers of his ministry attended the meeting and the presidents of the banks were surprised over the currency devaluation. He said the heads of banks spoke openly and some of them conceded they were also in a state of shock over the sudden fall in the currency value. The minister said the bank representatives also claimed to have been misled.
He backtracked from his earlier statement in which he attributed the sharp decline in the rupee value to exploitation of the political situation by speculators, saying it was his initial impression but “obviously that has been totally negated”.
The minister said the exchange rate was no longer pegged with the dollar as it used to be before 1999 and now the exchange rate was now market based. He said “it was painful for him to say that the surprising slide in the currency value was caused by a communication gap about a decision of an individual that was not even in the knowledge of the deputy governor. Nobody, no individual, even myself, has the authority to take such a major decision”. He did not elaborate on what the communication gap was.
This has far-reaching consequences for the national economy which was in expansionary mode and moving towards six per cent growth rate, he said. “Nobody has the authority to take such a major decision for artificial adjustment,” he emphasised repeatedly, insisting that open markets make adjustments in routine and gradually and there was no reason for such a slide when foreign exchange reserves were higher than $2bn up from $9bn a few years ago.
Responding to a question, Mr Dar said the market had made self-correction first thing in the morning and returned to slightly higher than Rs105 against the dollar. He said the current account deficit was not the responsibility of the central bank. “The market adjusted itself before the meeting started,” he said.
Meanwhile in Karachi foreign exchange markets heaved a sigh of relief as signs of normalcy returned. Foreign exchange crept back into the open markets after completely disappearing on Wednesday. Bankers too were relieved that an impending spell of uncertainty had been averted, although many continued to insist that the pressures building on the rupee are substantial. “Devaluation is inevitable” one treasury source told Dawn, a sentiment echoed by several others.
Besides, social media and a few broadcast outlets were alive with rumours that a new SBP governor could be nominated by Thursday night.
Published in Dawn, July 7th, 2017