For entrepreneurs considering Pakistan’s emerging lithium-ion battery recycling industry, the first question is usually straightforward: how much capital is required?
The answer is less straightforward. There is no single price tag for entering battery recycling because recycling is not one business. It is a chain of activities ranging from collection and dismantling to mechanical processing and sophisticated chemical recovery. The amount of capital required depends largely on where an investor chooses to enter that chain.
This distinction is particularly important for Pakistan. The image of battery recycling as a large chemical plant requiring hundreds of millions of dollars can discourage smaller investors from exploring the sector. In reality, businesses can enter at considerably different levels of technical and financial complexity.
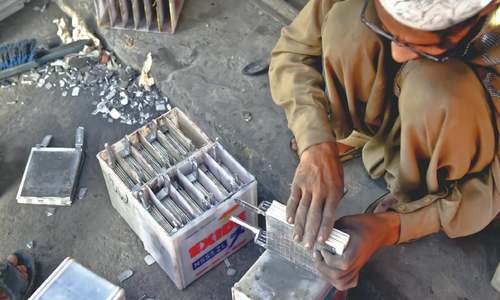
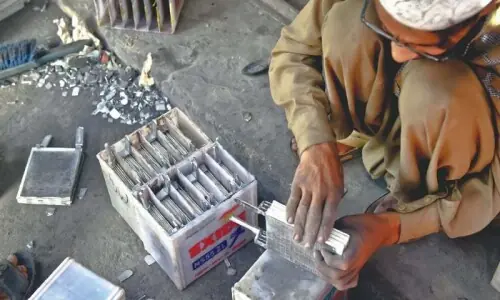
The first level is collection, sorting, diagnostics and dismantling. Used batteries must be collected from households, solar installations, electric vehicles, telecommunications systems and industrial users before they can be recycled. They then need to be identified by chemical analysis, tested, safely discharged, and assessed for reuse or recycling.
Beginning at the lower and middle parts of the chain may offer a more realistic route to investing in this sector
This represents the lowest-capital entry point. Investment is primarily required for secure storage, diagnostic and discharge equipment, insulated tools, fire protection, material-handling systems and safe transportation. The business model can generate revenues through collection contracts, resale of reusable batteries, second-life applications and supplying sorted batteries to larger recycling facilities.
The second level is mechanical processing. Here the investment becomes significantly larger. Batteries are discharged and dismantled before cells are shredded in controlled conditions. Mechanical separation then recovers materials such as copper, aluminium, steel and plastics while producing black mass containing the battery’s active materials.
International estimates illustrate the difference in scale. A technical business case prepared by South Africa’s Mintek estimated capital expenditure of approximately $180,000 for a 100-tonne-per-year black-mass processing operation. Increasing capacity to 9,000 tonnes per year raised estimated capital expenditure to around $3.5 million. These figures are international engineering estimates rather than quotations for Pakistan, but they demonstrate that mechanical processing can provide an intermediate route between small-scale dismantling and full chemical refining.
The third level involves recovering metals from black mass. Hydrometallurgical facilities use chemical processes to recover lithium, nickel, cobalt, manganese and other materials. They require reactors, filtration and separation systems, chemical storage, laboratories, wastewater treatment and environmental controls.
The same international study estimated capital expenditure of approximately $660,000 for a 100-tonne-per-year hydrometallurgical facility, increasing to around $12.3 million at 9,000 tonnes annually.
Pyrometallurgical processing, which relies on high-temperature treatment, was estimated at approximately $1.06m at 100 tonnes and $20.7m at 9,000 tonnes per year. Again, these should be treated as international benchmarks rather than investment quotations for Pakistan.
At genuinely industrial scale, the numbers become much larger. A European engineering study for a 21,000-tonne-per-year hydrometallurgical recycling hub estimated capital expenditure of about $320m, while an integrated operation combining mechanical pre-processing and refining was estimated at approximately $440m.
These differences explain why asking for the “minimum capital” required for battery recycling can be misleading. A better question is: which part of the recycling chain offers the most practical entry point?
For Pakistan, beginning at the lower and middle parts of the chain may offer a more realistic route. Collection networks, battery diagnostics, second-life assessment, dismantling and eventually black-mass production can build commercial experience before firms move towards sophisticated metal recovery.
Capital alone, however, does not determine viability. A recycling plant needs sufficient batteries flowing through it. Research consistently shows that recycling economics depend heavily on throughput, battery chemistry, collection and transportation costs, energy and material prices, and the value of recovered metals. Economies of scale can significantly improve commercial feasibility.
Chemistry matters as well. Batteries rich in nickel and cobalt can produce more valuable recovered materials, while lithium iron phosphate batteries contain fewer high-value metals. A plant designed around assumptions about today’s battery waste may therefore face different economics as Pakistan’s battery mix changes.
This is why the first investment before building a large recycling facility should arguably be information. Pakistan needs reliable estimates of how many lithium-ion batteries are already entering the market, their chemistries, where they are being deployed and when they are expected to reach end of life. Without a predictable feedstock pipeline, even technically sophisticated facilities can struggle commercially.
For Pakistani entrepreneurs, therefore, battery recycling need not begin with a multimillion-dollar refinery. It can begin with organised collection, diagnostics and safe dismantling, followed by mechanical processing as volumes increase and eventually chemical recovery when sufficient feedstock and technical capabilities exist.
The capital requirement grows at every stage, but so does the potential value captured. The lesson for investors is simple: do not begin by asking how much a battery recycling plant costs. Begin by deciding which part of the battery recycling business you want to build.
The writer is a research associate at the Centre of Excellence-CPEC under Pide and the Ministry of Planning and Special Initiatives.
Email: sapna.vk@pide.org.pk
Published in Dawn, The Business and Finance Weekly, August 31st, 2026