KARACHI: The Sindh High Court has ruled that the liability to pay default surcharge under the Sindh sales tax on services law was a strict statutory obligation of a compensatory character.
The SHC also noted that proof of wilfulness or mens rea was not a condition for its imposition, and neither officers of the Sindh Revenue Board (SRB), nor the commissioner or appellate tribunal, were vested with any power to waive, reduce or defer such liability on grounds of hardship, equity or absence of intention.
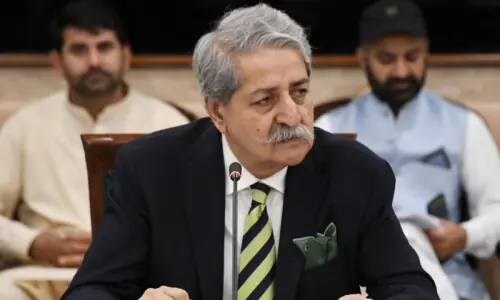
A two-judge SHC bench comprising Justice Agha Faisal and Justice Shah Nawaz Memon further observed that it did not underestimate the disruption caused by Covid-19 to commercial life in Sindh, but sympathy was not a source of jurisdiction and there was no equity about a tax.
The bench issued the judgement while disposing of 12 identical special sales tax reference applications filed by the SRB against orders of the appellate tribunal, which had waived default surcharge imposed by the SRB on a dozen industries, banks and other private firms. The tribunal had set aside the surcharge on the ground that the default had not been shown to be wilful and there was no mens rea.
In its judgement, the SHC noted that the Sindh Sales Tax on Services Act itself provided a route to obtain pandemic relief, but it was not the route the respondents had chosen, as Sections 17(3) and 45 empowered the SRB to prescribe a different time for payment and exempt surcharge.
Published in Dawn, August 23rd, 2026