LHC curtails federal tax ombudsman, president’s jurisdiction in tax matters
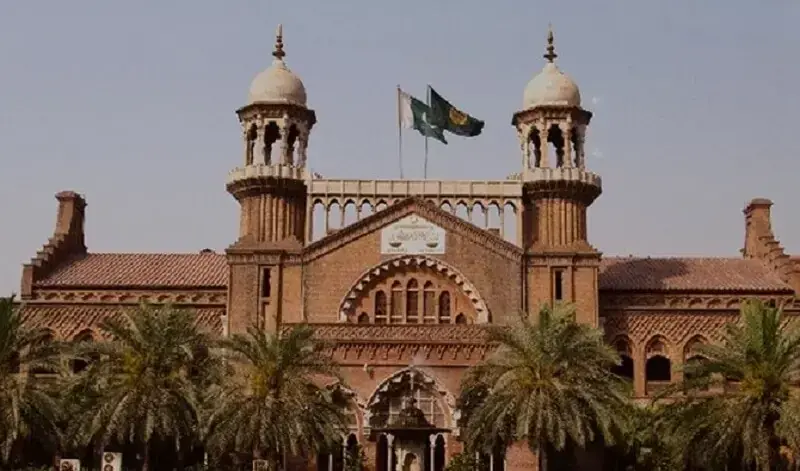

LAHORE: The Lahore High Court has set aside orders of the Federal Tax Ombudsman (FTO) and the president, ruling that they had no jurisdiction to entertain a complaint about delayed adjudication of seized goods, since the matter fell squarely within the domain of the statutory tax authorities and appellate forums.
An LHC division bench comprising Justice Jawad Hassan and Justice Abid Hussain Chattha issued the judgement, allowing a petition filed by the Commissioner Inland Revenue, Multan Zone, against a private cigarette dealer, the FTO, and the President’s Secretariat.
According to case details, the Directorate of Intelligence and Investigation (Inland Revenue), Multan, acting on secret information, obtained a search warrant and with police assistance, recovered 641 cartons of allegedly illicit, non-duty-paid and counterfeit cigarettes from the dealer’s premises.
The dealer’s representative could not produce invoices or records proving duty payment and a show-cause notice was issued to him.
Court sets aside orders on delayed adjudication of seized cigarettes
Instead of responding to the notice, the dealer filed a complaint with the FTO under Section 10(1) of the Federal Tax Ombudsman Ordinance, 2000, alleging that the tax department had unduly delayed adjudicating the seized goods, causing him financial losses.
The FTO entertained the complaint and directed that adjudication proceed before the appropriate forum.
The tax department’s representation against this order was subsequently dismissed by the president, prompting the department to approach the LHC.
Justice Hassan, the author of the judgement, held that jurisdiction “goes to the root of the matter,” and that an order passed without lawful authority is void from the outset.
Examining Section 9 of the FTO Ordinance, the bench observed that while the ombudsman is empowered under Section 9(1) to investigate allegations of maladministration by the Revenue Division or its employees, that power is not absolute.
It explains that Section 9(2)(b) expressly bars the FTO from inquiring into matters relating to assessment of income or wealth, determination of tax or duty liability, or classification and valuation of goods, wherever the law already provides a remedy of appeal, review or revision.
The bench held that the FTO’s role is to provide an independent, expeditious remedy against maladministration, “without allowing the FTO to assume the jurisdiction of statutory appellate or adjudicatory forums”.
The bench noted that had the matter proceeded through the ordinary statutory route, the dealer would have had a right of appeal under section 33 of the Federal Excise Act, 2005, with further appeal to the appellate tribunal under Section 34 — forums before which he could have raised every question relating to the seizure, the legality of the goods and any duty or tax liability.
The bench held that the FTO could not step into this space merely because the dealer alleged that adjudication had been delayed.
The bench allowed the petition and set aside both orders passed by the FTO and the president, dismissing the department’s representation against it.
Published in Dawn, September 25th, 2026