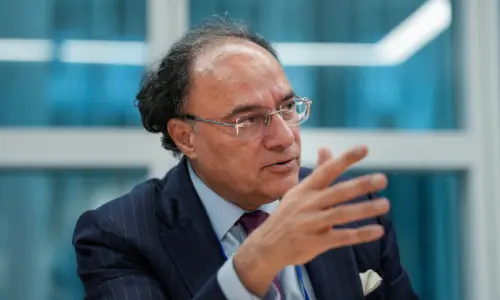
Saudi Arabia has pledged an additional $3 billion in deposits for Pakistan and has extended its existing $5bn facility for a further three years, Finance Minister Muhammad Aurangzeb announced in Washington.
Pakistan will reportedly return a $3.5bn loan to the UAE this month, putting pressure on its reserves and risking breaches of its International Monetary Fund (IMF) programme targets.
He added that the existing $5bn Saudi deposit would no longer be subject to the previous annual rollover arrangement and would instead be extended for a longer term.
The finance minister made the announcement while speaking to media representatives in Washington, DC, on the sidelines of the World Bank–IMF Spring Meetings 2026, where he shared key details on Saudi financial support for Pakistan and the government’s external financing strategy.
According to the finance czar, the support from the kingdom comes at a “critical time” for Pakistan’s external financing needs and would help “reinforce foreign exchange reserves and strengthen the country’s external account”.
Aurangzeb reiterated the government’s commitment to maintaining reserves in line with its market obligations and targets under the IMF-supported programme, including the goal of building reserves to around $18bn — equivalent to roughly 3.3 months of import cover — by the end of the fiscal year.
The finance minister noted that Pakistan had successfully repaid $1.4bn in debts last week, including a Eurobond, terming it a “non-event”, and reaffirmed the government’s commitment to meeting all upcoming external obligations and maturities on time.
He said the country’s external financing plan was clearly laid out and was being implemented in a responsible and disciplined manner.
Aurangzeb recalled his “detailed meeting” with his Saudi counterpart Mohammed bin Abdullah al Jadaan last week in Islamabad, adding that the State Bank of Pakistan (SBP) governor and Pakistan’s envoy to Washington were also in attendance.
He noted that the government had “deliberately refrained from commenting publicly in the absence of formal communication, despite media reports and speculation, as such matters required clarity and joint understanding before being shared”.
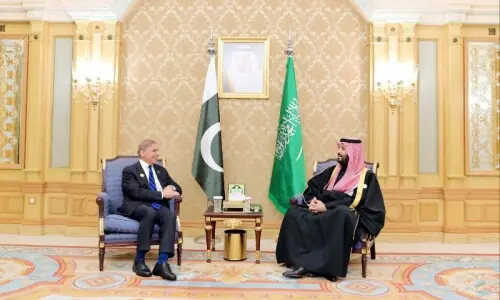
Aurangzeb expressed gratitude to the leadership of Saudi Arabia, particularly Crown Prince Mohammed bin Salman, the finance minister and the Saudi vice finance minister, for their continued support and close cooperation, and appreciated the efforts made to bring the package to fruition.
The finance minister also acknowledged the role of Pakistan’s political and economic leadership in securing and operationalising the support. He thanked the prime minister, the field marshal, the deputy prime minister, the SBP governor, and others for their contributions and coordination.
Aurangzeb said that sentiment and confidence were currently of “critical” importance, noting that Pakistan was receiving strong appreciation from international financial institutions, including the IMF and the World Bank, as well as from institutional investors and counterparts in Washington.
He said the international community had particularly acknowledged Pakistan’s recent diplomatic and facilitative role in enabling dialogue between parties that had not held face-to-face talks for decades.
He added that this appreciation, along with Saudi Arabia’s timely financial support, had provided Pakistan with renewed momentum and confidence for the economy and the external account, including its commercial aspects.
The finance minister also stated that Islamabad was advancing its broader external financing agenda, including the recently announced Global Medium-Term Note (GMTN) programme and the planned inaugural Panda Bond issuance.
In his statement, the finance minister concluded by reaffirming the government’s commitment to macroeconomic stability, meeting external obligations, maintaining reform momentum and sustaining engagement with bilateral and multilateral partners.
He added that a more detailed interaction with the media would be held at the end of the visit.
A day ago, speaking on the sidelines of the IMF/World Bank annual spring meetings, Aurangzeb said the country could manage all debt repayments, and that its reserves remained at roughly 2.8 months of import cover.
Maintaining at least that level, he said, would be “an important aspect of our overall macro stability as we go forward”.
“We are looking at Eurobond, we are looking at Islamic sukuk, we are looking at dollar-settled rupee-linked bonds,” Aurangzeb said, adding that they expected to issue Eurobonds this year and are also exploring commercial loans.
Aurangzeb said while the country had not yet requested any additions or changes to its $7bn IMF programme due to the economic shocks of the war in the Middle East, it was a potential option.