Economy can weather Iran war risks: SBP chief
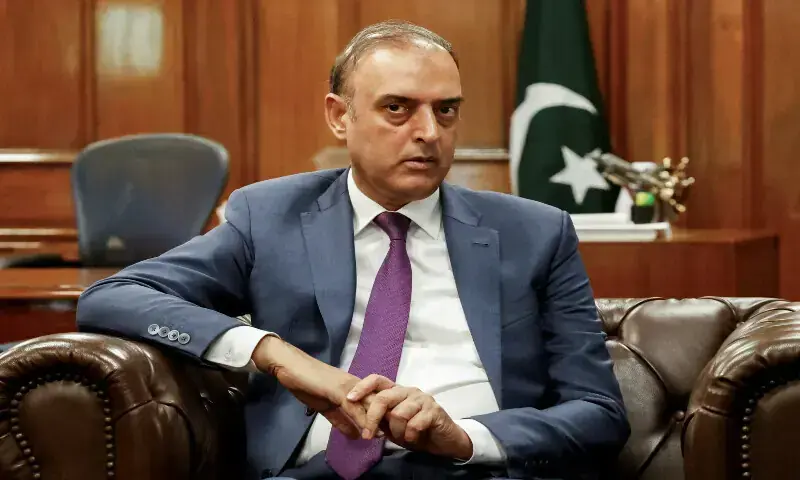

• Jameel Ahmad says macroeconomic indicators improved faster than expected at start of fiscal year
• Claims prudent monetary, fiscal policies stabilised inflation, strengthened buffers
KARACHI: State Bank of Pakistan (SBP) Governor Jameel Ahmad has said the country’s key macroeconomic indicators have improved faster than anticipated at the start of the fiscal year, owing to a prudent mix of monetary and fiscal policies that helped stabilise inflation and strengthen external positions.
While the ongoing conflict in the Middle East has introduced new risks and heightened uncertainty about the macroeconomic outlook, he said, the economy is relatively better positioned than during previous crises to manage these challenges.
The SBP governor was speaking at meetings with senior executives of leading global financial and investment institutions, including JP Morgan, Barclays, Citibank, Jefferies and Franklin Templeton, as well as major credit rating agencies such as Fitch, Moody’s and S&P Global.
These engagements took place on the sidelines of the IMF-World Bank spring meetings held from April 13 to 18 in Washington. Mr Ahmad also held key meetings with the leadership of the IMF and World Bank Group.
He informed the participants about the significant progress made by Pakistan in stabilising the economy prior to the Middle East conflict, saying that a prudent monetary and fiscal policy mix had helped reduce and stabilise inflation within the target range, while strengthening fiscal and external buffers.
The governor said that during the first nine months of the current fiscal year, inflation averaged 5.7 per cent, the external current account remained in surplus, and SBP’s foreign exchange reserves rose to $16.4 billion, mainly due to central bank purchases from the interbank market.
He said reserves are expected to increase further to around $18bn by June 2026, supported by continued SBP purchases and the realisation of official inflows, including fresh bilateral arrangements.
The governor said improved macroeconomic stability has supported a gradual, sustainable and broad-based recovery in growth. Real GDP expanded by 3.8pc in the first half of FY26, compared to 1.8pc in the same period last year.
He added that prudent policy measures have strengthened Pakistan’s initial conditions compared to earlier external shocks, such as the Russia-Ukraine conflict in early 2022.
Mr Ahmad said these improved fundamentals place the economy in a stronger position to face challenges arising from recent developments in the Middle East, including a sharp rise in global energy prices, freight and insurance costs.
He reaffirmed that the SBP and the government remain committed to maintaining price stability and will take necessary measures to safeguard macroeconomic stability, adding that monetary policy remains cautiously prudent, with the real policy rate significantly positive.
He said the government has posted primary fiscal surpluses and, in response to the ongoing conflict, introduced targeted subsidies and demand-management austerity measures.
IMF agreement
The governor also referred to the staff-level agreement with the IMF for the third review of the Extended Fund Facility and the second review of the Resilience and Sustainability Facility, as well as a credit rating reaffirmation by a major agency, describing these as independent endorsements of the government’s and SBP’s reform commitment.
During his visit, Mr Ahmad also engaged with the Pakistani diaspora and global stakeholders at the Remittances and Roshan Digital Account (RDA) Roadshow. He highlighted that RDA inflows have surpassed $12.4bn across more than 917,000 accounts.
He also outlined recent enhancements to the RDA regulatory framework, including the inclusion of non-resident entities, aimed at further integrating Pakistan into global financial markets and attracting a wider range of foreign investment.
Published in Dawn, April 19th, 2026