
KARACHI: The Pakistan Stock Exchange (PSX) on Thursday attracted renewed buying interest in select sectors, helping the benchmark KSE-100 index partially recover overnight losses, despite persistent uncertainty on the economic front due to geopolitical concerns amid elevated crude oil prices.
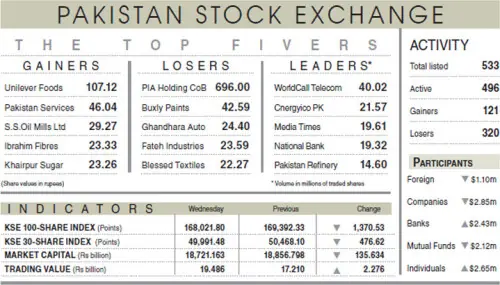
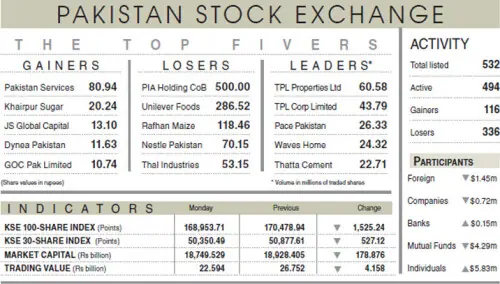
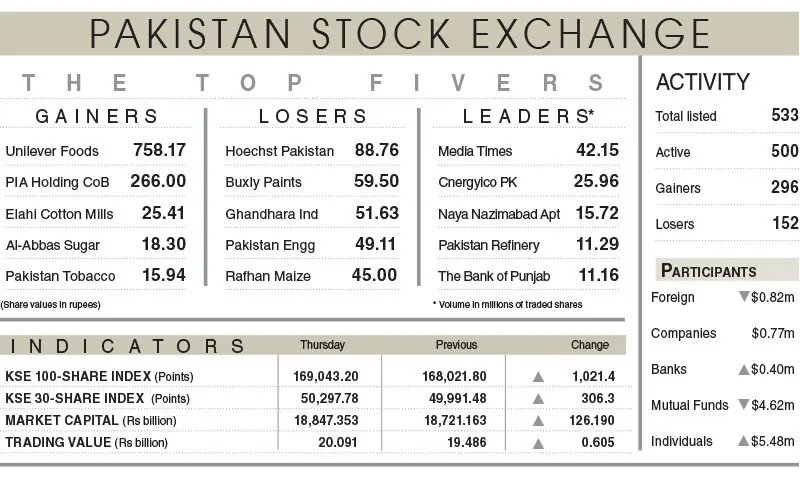
Topline Securities Ltd said the index rebounded, gaining 1,021.40 points, or 0.67 per cent, to close at 169,043.20, partially recovering from the previous session’s sharp decline. The benchmark traded between 168,223 and 169,577, reflecting elevated volatility despite the positive close.
The recovery was supported by selective buying in key index-heavy stocks after the recent correction. However, market sentiment remained cautious amid ongoing focus on global oil prices, geopolitical developments, domestic macroeconomic indicators, and institutional flows.
Ali Najib, Deputy Head of Trading at Arif Habib Ltd (AHL), said investor sentiment improved after US President Donald Trump’s remarks suggesting the war with Iran could be nearing an end, with easing oil prices further supporting sentiment. Reports of additional Saudi crude cargoes being routed through Oman helped ease concerns about potential supply disruptions.
On the corporate front, National Bank informed the PSX that the Federal Constitutional Court of Pakistan announced its judgment on Wednesday (Sept 16) on pensioners’ entitlement to government-announced pension increases and dismissed the bank’s appeal.
On the index contribution front, Pakistan Petroleum, United Bank, Mari Energies, Bank Alfalah, Habib Bank, Engro Holdings, Lucky Cement, Oil and Gas Development Company, Meezan Bank, and Maple Leaf Cement Factory were the top positive contributors, collectively adding 717 points to the index.
Market activity remained relatively stable, with trading volume edging up 8.48pc to 386.3 million shares and the traded value rising 3.10pc to Rs20.09bn. Media Times Ltd led the volume chart with 42m shares.
Analysts suggest that buying interest may revive if geopolitical tensions ease and oil prices decline.
Nonetheless, high energy prices, external-sector risks, and the upcoming IMF review will continue to be significant factors shaping market trends.
Published in Dawn, September 18th, 2026